
Chris Chase
Licensed Florida insurance broker · FL License #G193830 · NPN 21407586
Last reviewed October 2026
The short version
- Insurance companies look at claims you have filed and claims filed on the home before you owned it.
- Water and liability claims usually weigh more than a single weather claim.
- Florida law limits a company’s ability to drop you over one water claim.
- You generally have one year from the date of loss to report a property claim in Florida.
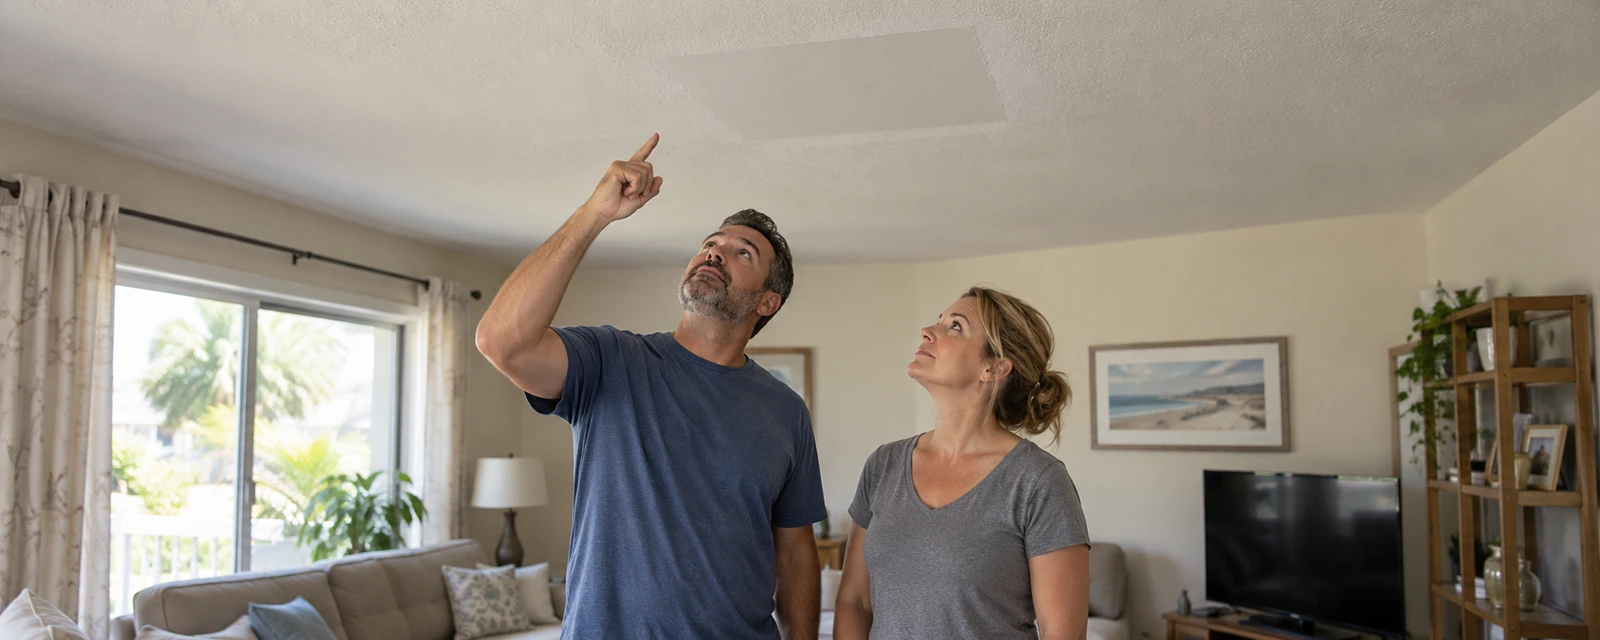
Insurance is there to be used. But every claim also becomes part of a record, and that record is one of the first things a company looks at when you apply for a new policy or come up for renewal.
I get two questions about this all the time. “Will filing this claim hurt me?” and “Why am I being asked about a claim I never filed?” This article answers both, and it sticks to what Florida law says and what I see when I quote homes.
In this article
Two histories: yours and the home’s
When you apply for home insurance, a company is interested in two separate things.
- Your history. Claims you have filed as a homeowner or renter, at this address or a previous one.
- The property’s history. Claims filed on the house itself, including by people who owned it before you.
That second one is the surprise. A home that had water damage under a prior owner can raise questions for the next buyer, because the company wants to know the damage was properly repaired and the cause was fixed.
Insurance companies share claim information through industry claim databases. When you apply, the company can pull a report showing claims tied to you and to the address. That’s why the application questions about prior losses need to be answered accurately. The company is going to see the record either way.
Which claims weigh the most
Not all claims are viewed the same way. Each company sets its own rules, but the pattern I see is consistent.
Water claims
Water damage that isn’t from weather, such as a burst supply line, a leaking water heater or a failed drain, gets the most attention. Companies see it as something that can happen again in the same house, especially if the plumbing is older. More than one water claim in a few years makes a home noticeably harder to place.
Liability claims
A claim where someone was injured, such as a dog bite or a fall, is taken seriously. Companies will often ask what has changed since then.
Theft and fire
These are looked at case by case. A company will usually want to know the cause and whether it has been addressed.
How far back do companies look?
It depends on the company. Applications commonly ask about losses in the past three to five years. The number of claims in that window matters, and so does the type. One claim rarely closes every door. Two or three in a short period will narrow your choices and can raise your price.
What Florida law protects
Florida has some specific rules that work in your favor.
Deadlines for reporting a claim
Florida shortened these deadlines in recent years, and many homeowners haven’t heard. Under section 627.70132 of the Florida Statutes:
- A new claim or a reopened claim must be reported to the insurance company within 1 year after the date of loss.
- A supplemental claim, meaning a request for more money on a claim already filed, must be reported within 18 months after the date of loss.
For hurricanes, the date of loss is tied to when the storm made landfall. The point is simple: if you have damage, don’t sit on it. Waiting can cost you the claim entirely.
Should you file a small claim?
This is your decision, and I’ll never tell you not to use coverage you’re paying for. This is how I’d think it through.
- Get a repair estimate first, if the situation allows. You need a real number.
- Compare the estimate with your deductible. If the repair is $2,500 and your deductible is $2,500, a claim pays nothing and may still go on your record.
- Think about what kind of loss it is. A sudden, serious loss is exactly what the policy is for. A small repair close to your deductible is a closer call.
- Don’t delay emergency steps. Stop the water, protect the property and take photos, whether or not you end up filing.
- Remember the deadline. Deciding to wait is fine. Forgetting for a year isn’t.
Calling your agent to ask a general coverage question is different from reporting a loss to the insurance company. If you aren’t sure whether to file, call me first and I’ll talk it through.
If you have claims and need a new policy
A claim history doesn’t make you uninsurable. It means the paperwork matters more. What helps:
- Proof of repairs. Invoices, permits and photos showing the damage was fixed.
- Proof the cause was addressed. A new water heater, replaced supply lines, a new roof.
- A current four-point inspection on an older home, showing the systems are in good condition.
- Accurate answers. A claim you forgot to mention looks worse than one you explained.
- An independent agent. Companies don’t all weigh claims the same way, so checking several is the whole point.
Common questions
Will one claim make my insurance go up?
It can, depending on the company and the type of claim. Weather claims are generally viewed differently from water or liability claims. I can’t predict a specific increase.
Can my company drop me for filing a water claim?
Florida law says a single water damage claim can’t be the sole reason for cancellation or nonrenewal, unless you didn’t take steps the insurer reasonably asked for to prevent another one.
Why does the application ask about claims before I owned the house?
Because companies look at the property’s history as well as yours. They want to know prior damage was repaired.
How claims are weighed varies by company. This article is general information, not legal advice. For questions about a specific claim, read your policy or contact the Florida Department of Financial Services.
Official sources
- Florida Statute 627.4133: cancellation and nonrenewal
- Florida Statutes 627.70132, notice of property insurance claim
- Florida Statute 627.701: hurricane deductibles
- Florida Department of Financial Services: homeowners insurance overview
Keep reading
- Water Damage, Plumbing, and Older Homes
- Why Is My Hurricane Deductible So High?
- Four-Point Inspections and Home Insurance
- Can I Switch Insurance Companies Before My Policy Expires?
Related coverage: homeowners insurance and flood insurance.
Not sure where you stand? Ask me.
Request a quote or call me to review your options. You’ll talk to a real person.